The 2026–2027 Ontario Enhanced HST Rebate: A Historic Game-Changer for New-Build Buyers
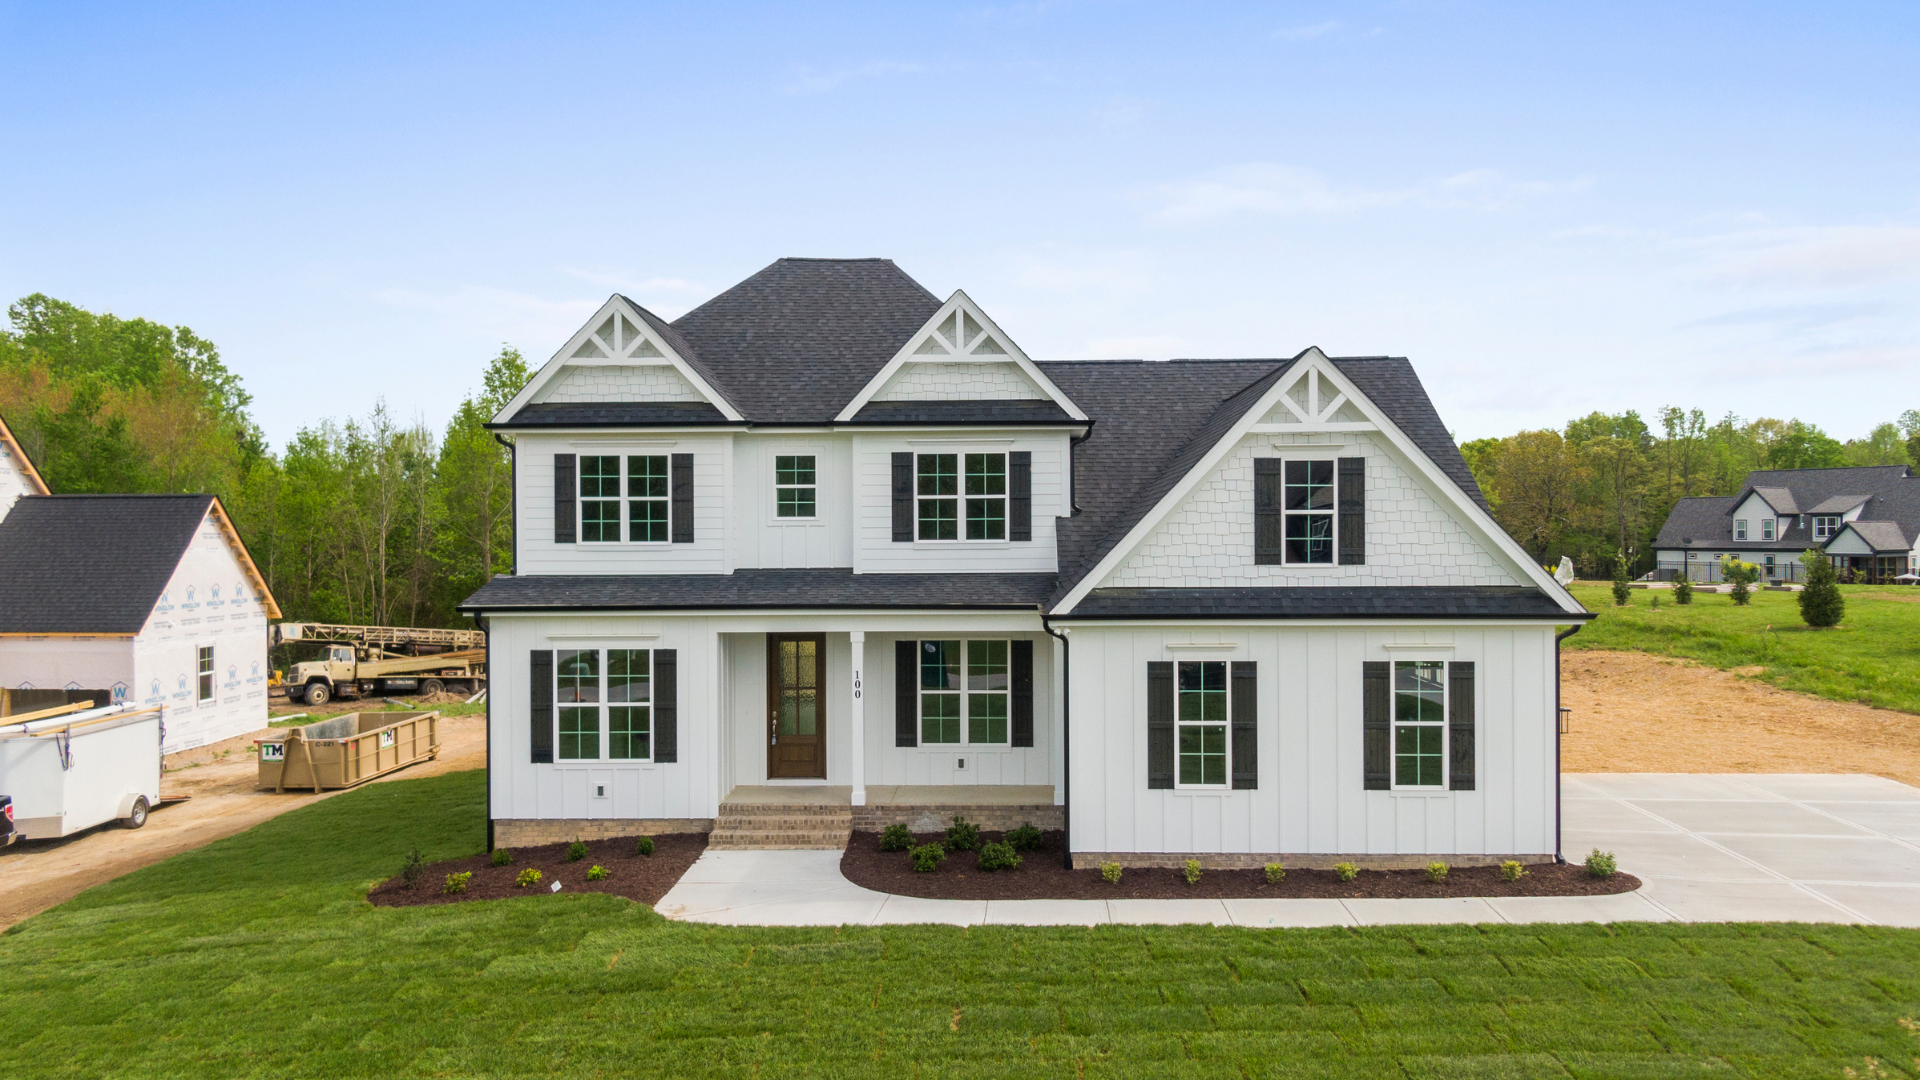
If you are considering buying a newly constructed home, townhouse, condo, or modular property in Ontario, a temporary tax reform has dramatically altered the financial equation.
Under the 2026–2027 Ontario Enhanced New Housing Rebate (ENHR) framework, enacted in partnership with the federal government, eligible buyers can effectively eliminate the full 13% Harmonized Sales Tax (HST) on qualifying new homes valued up to $1 million. This creates up to $130,000 in direct tax savings, narrowing the cost gap between buying a brand-new build and purchasing a resale property.
Here is a plain-language guide to how this temporary HST rebate works, who qualifies, and how the savings apply at closing.
1. Key Legislative Windows and Rules
To capture this temporary tax relief, your transaction must fall within strict legislative timeframes:
-
Signing Window: Your binding Agreement of Purchase and Sale (APS) with the builder must be signed between April 1, 2026, and March 31, 2027.
-
Construction Start Deadline: For builder-constructed homes, physical construction must begin on or before December 31, 2028 (or between April 1, 2026, and March 31, 2027, for owner-built homes).
-
Completion Deadline: The home must reach substantial completion (defined by the CRA as at least 90% completed and ready for occupation) on or before December 31, 2031.
2. Who Qualifies for the Enhanced Rebate?
Unlike traditional first-time home buyer incentives, the Enhanced HST Rebate is accessible to a much broader group of buyers:
-
First-Time Home Buyers: Fully eligible.
-
Repeat Home Buyers: Fully eligible, provided the newly built home will serve as your (or a close relative's) primary place of residence.
-
Real Estate Investors: Eligible under the Enhanced New Residential Rental Property Rebate (NRRPR) rules, provided the property is leased for long-term residential use under a minimum 12-month lease agreement.
3. How the Savings Scale by Home Price
In Ontario, new homes are subject to 13% HST (comprising an 8% provincial portion and a 5% federal portion). The Enhanced HST Rebate offsets both portions through the provincial ENHR and the Ontario New Home Affordability Payment (ONHAP) top-up.
Here is how the rebate scales across different purchase price tiers:
-
Homes Up to $1,000,000: Full 100% elimination of the 13% HST. For example, on a $900,000 new construction home, the standard 13% HST liability equals $117,000. Under this framework, the rebate covers the full $117,000, reducing your net HST tax bill to $0.
-
Homes Between $1,000,001 and $1,500,000: The rebate reaches its maximum statutory cap and provides a flat $130,000 tax reduction. On a $1.2 million build, the $156,000 HST bill is reduced by $130,000, leaving only $26,000 payable.
-
Homes Between $1,500,001 and $1,850,000: The rebate gradually phases down on a declining sliding scale from $130,000 down to $24,000. For instance, a home priced at $1.675 million receives a $77,000 tax rebate.
-
Homes Priced Over $1,850,000: Higher-end builds revert to the standard legacy provincial rebate floor of $24,000.
4. How the Savings Compare to the Old System
Prior to April 1, 2026, new home buyers in Ontario received significantly less tax relief. Under the old system, federal GST relief capped out at just $6,300 (phasing out completely above $450,000), and the Ontario provincial rebate was capped at $24,000.
Here is a clear look at the net buyer savings delivered by the 2026–2027 enhanced rules compared to the old rebate rules:
-
$600,000 New Build: Old rebate provided $24,000. New enhanced rebate provides $78,000 (a net buyer savings increase of +$54,000).
-
$800,000 New Build: Old rebate provided $24,000. New enhanced rebate provides $104,000 (a net buyer savings increase of +$80,000).
-
$1,000,000 New Build: Old rebate provided $24,000. New enhanced rebate provides $130,000 (a net buyer savings increase of +$106,000).
-
$1,250,000 New Build: Old rebate provided $24,000. New enhanced rebate provides $130,000 (a net buyer savings increase of +$106,000).
-
$1,500,000 New Build: Old rebate provided $24,000. New enhanced rebate provides $130,000 (a net buyer savings increase of +$106,000).
5. Claiming the Rebate at Closing
In Ontario, agreements for new builds are typically written using "Stated Price Net of Rebate" (SPNR) terms. This means the builder credits the tax rebate directly to you on the Statement of Adjustments at closing, reducing your required cash payment, and then claims the funds back from the CRA.
To ensure your rebate is credited smoothly:
-
Complete CRA Forms: You and your builder must complete Form GST190 and Form RC7190-ON.
-
Consent Box for Federal Top-Up: Ensure you check the ONHAP information-sharing consent box on your form, which allows the CRA to pass details to ServiceOntario to issue the $50,000 federal portion.
-
Out-of-Pocket Safeguard: If updated CRA forms are not available on your exact closing day, you may need to pay the HST upfront and have your lawyer submit a direct refund claim with the CRA immediately afterward.
Because this temporary 13% HST elimination expires after March 31, 2027, prospective buyers looking at new construction should review contract dates closely with their real estate lawyer to lock in these substantial savings before the deadline passes.